A consulting company in Indonesia should be set up around the services it will actually invoice—not around the word ‘consulting.’ Strategy advice, marketing consulting, IT advisory, engineering services, tax consulting, legal work, recruitment, and other professional services can belong to different business classifications and regulatory frameworks.
Consulting Company Setup Process: The Short Answer
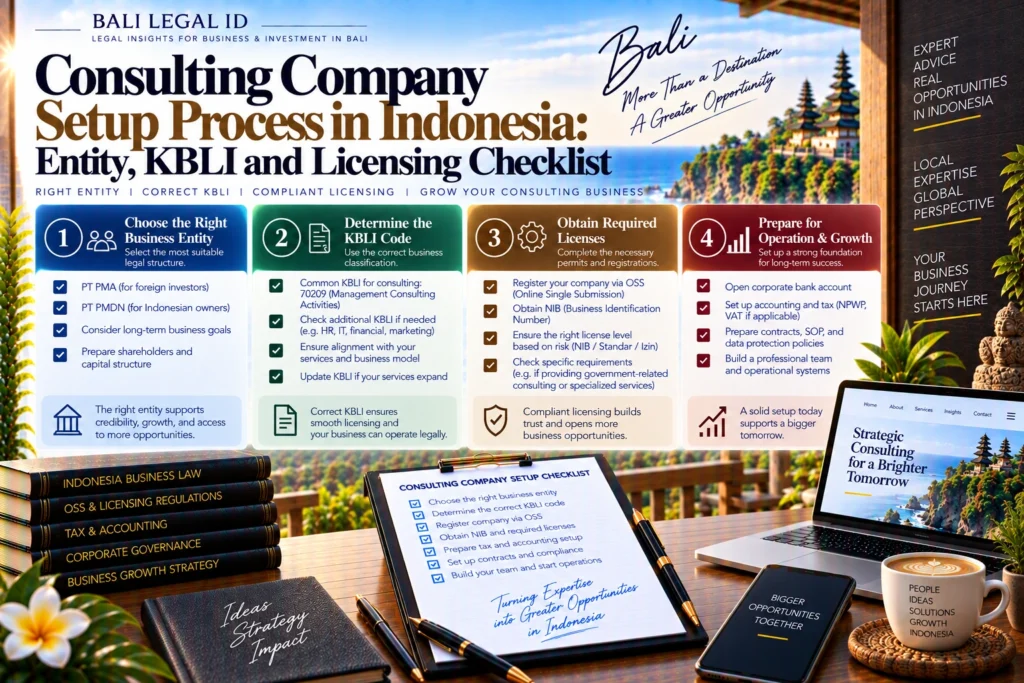
A practical consulting company setup process follows this order:
- define the exact consulting services and deliverables
- map each material service to the current KBLI 2025 classification
- choose the domestic or foreign-investment ownership structure
- establish the company through the applicable notarial and Ministry process
- complete OSS risk-based licensing for the selected activities
- align client contracts, proposals, invoices, and marketing with the registered scope
- prepare tax, accounting, beneficial-owner, and recurring compliance workflows
The most important decision is therefore not the company name. It is whether the registered activity accurately describes what clients will pay the company to do.
Step 1: Define Exactly What the Consulting Company Will Sell
Start by writing a list of billable services.
For example, a consulting company may provide corporate strategy, organizational design, HR advisory, marketing strategy, business-process improvement, feasibility studies, market-entry advice, technology consulting, or another specialist service. Those descriptions should be specific enough to test against the current KBLI.
Founders using older consulting references should recheck them because OSS records that KBLI 2020 code 70209 was split into two KBLI 2025 codes: 70203 and 70209.
That change makes it risky to copy an old deed, NIB, consultant template, or online article without checking the current classification.
Marketing Consulting and General Management Consulting Are Now Distinct
For a marketing-led consulting model, OSS describes KBLI 2025 code 70203 as Aktivitas Konsultansi Manajemen dan Bisnis Perdagangan, including advice and studies related to marketing strategy, brand development, sales value, and other marketing-management functions.
For broader management advisory, OSS describes KBLI 2025 code 70209 as Aktivitas Konsultasi Manajemen dan Bisnis Lainnya, covering areas such as strategy, organization, finance-related management decisions, human resources, production planning, efficiency, and management information.
A company providing both material marketing-consulting and wider management-advisory services should review whether both classifications belong in its company and OSS activity portfolio rather than assuming one code automatically covers the entire service catalogue.
Do Not Use Management Consulting as a Catch-All
The safest approach is to classify the professional activity, not the commercial label on the proposal.
A client may casually call legal advice, tax advice, software architecture, engineering studies, executive recruitment, advertising, or training ‘consulting,’ but that does not mean the management-consulting KBLI is automatically the right classification.
Before incorporation, compare each service line with its own current KBLI description. If the activity belongs to a regulated profession or sector, review that sector’s licensing and professional requirements separately instead of stretching 70203 or 70209 beyond their stated scope.
Bali Legal ID’s supplied article on choosing between KBLI 70209 and 70203 can be used as a more focused classification reference.
Step 2: Choose PT PMDN or PT PMA
Once the activities are clear, decide who will own the company.
A domestically owned consulting company can use the applicable Indonesian-owned company structure. Where foreign investment is involved, Article 5(2) of the Investment Law requires foreign investment generally to use an Indonesian limited liability company domiciled in Indonesia unless another law provides otherwise.
Do not finalize a foreign ownership structure from the word ‘consulting’ alone. The selected KBLI portfolio should first be checked against the current foreign-investment framework and any sector-specific restrictions that may apply to specialist professional services.
For the broader foreign-owned company sequence, Bali Legal ID’s PT PMA setup guide for Bali provides the general incorporation framework.
Foreign-Owned Consulting Companies Need a PMA Capital Plan
The current investment-administration framework is Permeninves/BKPM No. 5 of 2025, which JDIH BPK lists as in force from 2 October 2025 and as replacing the earlier 2021 BKPM OSS, licensing-procedure, and supervision regulations.
For an ordinary consulting PT PMA, Article 26 generally sets minimum total investment above IDR 10 billion excluding land and buildings per five-digit KBLI business field per project location, subject to the exceptions stated in the regulation.
The same regulation separately provides that minimum placed and paid-up capital for a PMA limited liability company is IDR 2.5 billion per company unless another applicable regulation provides otherwise.
Investment value and paid-up capital are different concepts. Neither should be confused with professional incorporation fees or the consulting firm’s monthly operating budget.
Step 3: Establish the Company Through the Notarial and SABH Process
After the activity, ownership, management, capital, company address, and shareholder structure are settled, the PT establishment can be prepared.
For a limited liability company, Permenkum No. 49 of 2025 is the current Ministry of Law establishment framework and JDIH BPK records that it revoked Permenkumham No. 21 of 2021.
The corporate filing itself uses the Ministry system because Article 5 requires establishment of a capital-association limited liability company to be submitted through a notary using the electronic establishment form in SABH.
The deed and supporting company data should describe the same consulting activities that will later be entered in OSS. If the actual business model changes materially during setup, revise the activity mapping before treating the original deed assumptions as final.
Step 4: Complete OSS Risk-Based Licensing
Company establishment creates the legal entity; it does not automatically complete every business licence.
After the company is established, PP No. 28 of 2025 is the current national Risk-Based Business Licensing framework and JDIH BPK records that it revoked PP No. 5 of 2021.
The OSS application should use the current KBLI, company data, project location, and business scale that match the actual consulting operation. Review the live OSS result for each activity rather than assuming that every type of consulting has identical licensing output.
Bali Legal ID’s OSS RBA registration guide provides broader context on the licensing stage after company formation.
Step 5: Build the Contract and Billing Model
Before the first client engagement, make the commercial documents match the registered business.
A consulting agreement should clearly identify the service, deliverables, responsibilities, fees, payment terms, confidentiality treatment, intellectual-property arrangements where relevant, termination mechanics, and dispute provisions appropriate to the engagement.
From a setup perspective, the key consistency check is simple: if the company is registered for management and business consulting, its website, proposals, contracts, and invoices should not quietly promise a materially different regulated professional service that was never classified or licensed.
If several consulting divisions will operate under one company, create a service map showing which KBLI supports each billable offering.
Step 6: Prepare Tax, Accounting and Compliance Workflows
Registration is only the beginning of operational compliance.
Before launch, decide how the company will issue invoices, record consulting revenue, document reimbursable expenses, manage withholding-tax documents received from clients, reconcile bank receipts, retain contracts and supporting records, and prepare recurring financial information.
Where the company provides several service lines, accounting records should make it possible to understand which activities generated the revenue. This is useful not only for financial control but also when management later reviews whether the registered activity portfolio still matches the real business.
Do not assume that a management-consulting classification itself authorizes the company to provide regulated tax, legal, accounting, engineering, or other professional services. Add those activities only after the applicable classification and regulatory framework have been reviewed.
Pre-Launch Consulting Company Checklist
Use this checklist before signing the first client contract:
| Area | Ready when | Stop and review when |
|---|---|---|
| Service scope | Every billable service is defined | The company is described only as ‘consulting’ |
| KBLI | Current KBLI 2025 matches the service | An old 70209 reference is being copied automatically |
| Marketing consulting | 70203 has been assessed where relevant | Marketing advisory is hidden inside a generic code without review |
| General management consulting | 70209 has been assessed where relevant | The company assumes 70209 covers every professional service |
| Ownership | PT PMDN or PT PMA route is settled | Foreign ownership is added after structure decisions are made |
| PMA capital | Investment and paid-up-capital rules are modelled | Regulatory capital is confused with setup fees |
| Corporate documents | Deed and SABH data match the activity plan | Company objects differ from the real service catalogue |
| OSS | Current licensing output is complete for each activity | Legal-entity approval is treated as the only licence |
| Contracts | Engagement documents match registered services | Contracts promise activities outside the licensed scope |
| Finance | Tax and accounting workflows are ready | Billing starts before records and responsibilities are defined |
The matrix is a planning tool. The live OSS result and any specialist-sector rules remain decisive for the actual company.
Conclusion
A consulting company should be built from the services outward.
First define what clients will pay for. Then select the current KBLI, decide whether the ownership structure is domestic or foreign, establish the company, complete OSS licensing, and align contracts, invoices, tax, and accounting with the same activity model.
For management and business consulting, the KBLI 2025 split between 70203 and 70209 is especially important because older references to 70209 no longer tell the whole story.
The practical rule is: do not register a generic consulting company first and define the services later—define the services first, then make the company documents, KBLI, OSS profile, contracts, and billing model describe the same business.
Map the Consulting Services Before the Company Is Filed
If you are planning a consulting company in Bali, Bali Legal ID can assist with a consultation to review the proposed PT PMDN or PT PMA structure, consulting activities, current KBLI selection, company documents, NIB OSS RBA registration, tax requirements, accounting setup, and related compliance issues.
The useful starting point is a list of the exact services the company intends to invoice so the entity and licensing structure can be built around the real consulting model.
For help scoping the documents and next steps for your business or transaction, contact Bali Legal ID about our business setup services in Bali.
Read More: Business Setup Bali for PT PMA, PT PMDN & OSS RBA Registration
FAQ consulting company setup process
What KBLI should a management consulting company use in 2026?
It depends on the service. OSS KBLI 2025 uses 70203 for management and trade-business consulting focused on marketing functions, while 70209 covers broader management and business consulting. The exact description should be matched to the services the company will actually provide.
Can I still use the old KBLI 70209 reference?
Do not copy it without review. OSS records that the old KBLI 2020 code 70209 was split into current KBLI 2025 codes 70203 and 70209.
Is marketing consulting under KBLI 70209?
Under the current OSS descriptions, marketing-focused management and business consulting is described under KBLI 70203, while 70209 covers other management and business consulting.
Can one consulting company use more than one KBLI?
Potentially, where it genuinely carries out several material business activities. Each additional activity should match the company’s deed, commercial model, and applicable OSS licensing rather than being added only as a precaution.
Can a foreign investor establish a consulting company in Indonesia?
Potentially through the appropriate PT PMA structure, but the exact consulting KBLI, foreign-investment eligibility, investment value, capital, and any specialist-sector requirements should be checked before incorporation.
What is the PT PMA investment requirement for an ordinary consulting company?
The current general PMA rule is more than IDR 10 billion in total investment excluding land and buildings per five-digit KBLI business field per project location, subject to the exceptions in the regulation.
What paid-up capital applies to a consulting PT PMA?
Permeninves/BKPM No. 5 of 2025 generally sets minimum placed and paid-up capital at IDR 2.5 billion per PMA limited liability company unless another applicable regulation provides otherwise.
Is Ministry approval enough to start consulting operations?
No. Company establishment and risk-based business licensing are separate stages. The company should review and complete the OSS licensing generated for its current KBLI activities before treating the setup as operationally complete.
Can a management consulting company also provide tax or legal advice?
Do not assume the management-consulting KBLI covers those services. Tax, legal, accounting, engineering, IT, recruitment, education, and other specialist activities should be classified and reviewed under the relevant current framework before they are offered.
What should be ready before the first consulting invoice is issued?
At minimum, the company should have an entity and licensing structure that matches the service, client-contract documentation, invoicing workflow, tax and accounting processes, and records capable of supporting the transactions being billed.
References & Sources
- Current OSS Conversion of Former Management Consulting Code 70209 — oss.go.id
- Current KBLI 2025 Marketing and Trade-Business Consulting Classification — oss.go.id
- Current KBLI 2025 Other Management and Business Consulting Classification — oss.go.id
- Current Ministry of Law Regulation for Limited Liability Company Establishment — peraturan.bpk.go.id
- Official Limited Liability Company Establishment Procedure — peraturan.bpk.go.id
- Current Status of Indonesia’s Investment Law — peraturan.bpk.go.id
- Official Investment Law Provision on Foreign Investment Business Form — peraturan.bpk.go.id
- Current Risk-Based Business Licensing Regulation — peraturan.bpk.go.id
- Current Investment and OSS Administration Regulation No. 5 of 2025 — peraturan.bpk.go.id
- Official PMA Investment Value and Capital Provisions — peraturan.bpk.go.id
Recommended Next Articles
- complete PT PMA setup process for foreign consulting founders — balilegalid.com
- OSS RBA registration and business licensing process — balilegalid.com
- general PT PMDN registration process for Indonesian-owned consulting companies — balilegalid.com