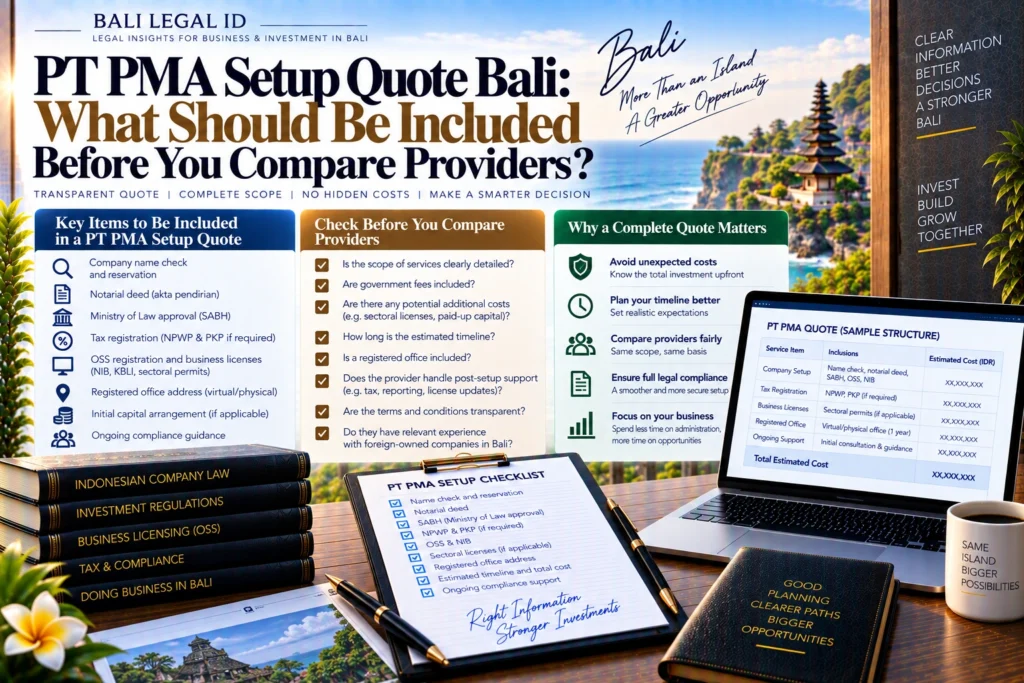
A PT PMA setup quote should be compared by deliverables, assumptions, exclusions, and responsibilities. This guide focuses on evaluating a provider's proposal; the separate cost guide addresses the overall formation budget.
Two PT PMA setup quotations can show similar headline prices while covering very different work. Before comparing providers in Bali, normalize the scope: shareholders, business activities, KBLI, project locations, capital, company address, corporate documents, SABH, OSS licensing, foreign documents, tax setup, and post-incorporation support.
The current investment and OSS framework includes Permeninves/BKPM No. 5 of 2025, which JDIH BPK lists as in force and as replacing the earlier 2021 BKPM regulations on the OSS system, licensing procedure, and investment supervision.
Corporate establishment is currently governed administratively by Permenkum No. 49 of 2025, which JDIH BPK lists as in force and as revoking Permenkumham No. 21 of 2021.
PT PMA Setup Quote Bali: The Short Answer
A useful PT PMA setup quote Bali should tell you four things clearly: what is included, what is excluded, what assumptions the price depends on, and what happens after the company is incorporated.
Do not compare providers only on one total price. A quote ending at the Ministry of Law establishment decision is commercially different from one that also covers OSS registration, NIB, activity-specific licensing, tax setup, document translation, amendments, or accounting handover.
For broader budgeting and sequence planning, the existing PT PMA formation cost and timeline guide addresses the overall formation budget and stages. This page focuses specifically on the contents of the provider quotation.
First Separate Capital From Formation Fees
The company’s regulatory financial commitments should not be presented as though they are fees paid to the incorporation provider.
The current regulation also provides that the placed and paid-up capital may not be transferred from the company’s account for at least 12 months after placement or payment, except for asset purchases, building construction, and/or business operations.
A quotation should therefore keep at least three columns mentally separate: company investment, company capital, and formation or advisory expenditure.
PT PMA Quote Scope Checklist
Use the following matrix to compare proposals against the same assumptions.
| Scope item | What the quotation should state | Common comparison issue |
|---|---|---|
| Initial structuring | Shareholders, directors, commissioners, activities, KBLI, locations and capital assumptions | A low quote may assume only one simple activity |
| Company-name and deed work | Drafting, notarial coordination and establishment deed | Check whether revisions are included |
| SABH incorporation | Submission and legal-entity establishment deliverable | Do not confuse this with complete operational licensing |
| Capital documents | What evidence or declarations the provider prepares or coordinates | Capital itself is not a provider fee |
| Beneficial-owner documents | Preparation or coordination of required ownership information | Confirm whether complex ownership structures cost extra |
| Foreign documents | Translation, authentication, apostille or legalization where applicable | Do not assume these third-party items are included |
| Company address | What address evidence is required and whether address support is included | Premises suitability is different from merely having an address document |
| OSS and NIB | Registration scope and included KBLI activities | One NIB project can still involve several licensing requirements |
| Business Licensing | Standard Certificate, permit or sector work actually included | ‘OSS included’ is too vague |
| Tax setup | Corporate tax-registration and account-setup scope | Ongoing tax compliance is a separate service unless included |
| Accounting handover | Chart of accounts, bookkeeping opening, document handover or other agreed work | Formation and ongoing accounting are different scopes |
| Post-incorporation compliance | LKPM, tax, bookkeeping or other recurring work | Confirm recurring fees and start date |
| Amendments | Whether corrections caused by changed client assumptions are included | Changes after signing can create new work |
| Government and third-party charges | Which items are included, reimbursable or excluded | A fixed professional fee may exclude external charges |
The table should make hidden scope differences visible. If two proposals use different assumptions, adjust the scope before comparing the totals.
1. Company Structuring and KBLI Review
The quotation should begin before deed drafting.
Ask the provider to confirm the proposed shareholders, share percentages, directors and commissioners, company activities, KBLI codes, project locations, investment assumptions, and capital structure. These inputs affect the deed and can also affect the OSS licensing result.
A quote based on one consulting activity should not automatically be compared with a quote covering several business activities, multiple project locations, or a regulated sector.
2. Deed, Notary and SABH Work
A proper quotation should account for notarial and corporate filing work because Article 5 of Permenkum No. 49 of 2025 requires establishment of a capital-association limited liability company to be submitted through a notary using the electronic establishment form in SABH.
The document scope matters because Article 6 requires supporting materials that include the establishment deed, evidence of capital, company-address information, and beneficial-owner documents, together with other applicable supporting records.
At the formal approval stage, Article 7 provides that the Minister through the Director General issues the legal-entity establishment decision when the application is received and delivers it electronically to the notary through SABH.
Your quotation should identify the concrete deliverables: the finalized corporate documents, notarial work being coordinated, SABH submission, and the establishment decision or equivalent completion file provided to the client.
3. Foreign Documents, Translation and Authentication
Foreign investors should ask for a document list before accepting a fixed price.
Depending on the shareholders, directors, corporate shareholders, issuing jurisdiction, document language, and use of the document, the project may involve translations or foreign-document authentication steps. Those requirements are fact-specific, so the quotation should state which document-handling work and which third-party costs are included rather than advertising a universal package assumption.
Ask whether the fee covers document review, translation coordination, apostille or legalization coordination where applicable, courier costs, corrections, and repeat submissions caused by incomplete source documents.
4. Company Address and Premises Assumptions
The quote should distinguish company-address documentation from premises and business-location compliance.
The establishment file includes address information, but a business location can also affect OSS, spatial, building, environmental, tourism, industrial, or other licensing questions depending on the activity.
Ask whether the provider is only preparing or checking company-address evidence or is also reviewing the actual project location for the intended activity. Those are different deliverables and should not be hidden under one line called ‘address included.’
5. OSS, NIB and Business Licensing
The quotation should also distinguish incorporation from business licensing because PP No. 28 of 2025 is the current Risk-Based Business Licensing regulation and JDIH BPK records that it revoked PP No. 5 of 2021.
A proposal that says only ‘OSS included’ is not specific enough for a meaningful comparison.
Ask the provider to identify which KBLI activities are included, whether NIB issuance is within scope, whether any Standard Certificate, permit, PB UMKU, basic requirement, or sector approval is included, and what happens if the OSS result requires additional evidence or verification.
The existing OSS registration and licensing guide can be used as a separate reference when reviewing how activity selection changes the licensing result.
6. Tax and Accounting Setup
A PT PMA formation quote should state clearly where the one-time setup ends and recurring compliance begins.
Depending on the agreed package, the scope may include corporate tax-registration coordination, tax-account setup, accounting opening work, bookkeeping preparation, financial-report support, or later tax compliance. These should be written as separate deliverables rather than assumed from the words ‘company setup.’
If you want ongoing support, ask for the recurring scope and fee separately. That makes it easier to distinguish formation expenditure from monthly or annual compliance costs.
Costs That Should Be Separately Identified
Ask the provider to identify third-party and variable items instead of hiding them behind a broad exclusion.
Depending on the project, these may include:
- government PNBP or filing charges
- notarial charges where separately priced
- sworn or professional translation
- apostille, legalization or authentication work where applicable
- courier and document-handling costs
- company-address or premises costs
- sector-specific licence or technical-assessment costs
- property or spatial review
- environmental or building-related work
- additional KBLI or project-location work
- amendments caused by changes in shareholders, activities, address or capital
- tax and accounting services after incorporation
Not every project requires every item. The useful question is whether each possible cost is included, excluded, reimbursable at cost, or quoted separately when triggered.
Questions to Ask Before Accepting a Quote
Use one written checklist when comparing providers:
- What exact entity and ownership structure does the quote assume?
- Which KBLI activities and project locations are included?
- Does the fee include deed drafting, notarial coordination and SABH establishment?
- Which shareholder, director, capital, address and beneficial-owner documents are included?
- Which foreign-document translations or authentication steps are included?
- Does the scope stop at incorporation or include OSS and NIB?
- Which activity-specific licences are included by name?
- Are government charges and third-party expenses included or separate?
- Does the quote include tax-registration coordination?
- Does it include accounting or bookkeeping setup?
- Are LKPM, tax filings, bookkeeping and other recurring obligations included after formation?
- How many client-requested revisions are included before additional fees apply?
- What happens if the client changes KBLI, location, shareholders or capital after work begins?
- What final documents and account access will be handed over?
- Which items are expressly excluded?
For a broader method of comparing professional proposals beyond PT PMA work, Bali Legal ID also has a legal service quotation checklist for Bali.
Use the PT PMA setup cost guide to frame the overall budget before comparing the fees and exclusions in a provider’s proposal. Check the proposed milestones against the PT PMA formation timeline and ask the provider to explain the assumptions behind its schedule.
Conclusion
A PT PMA setup quote in Bali should be judged by scope, not by headline price alone.
The most important distinction is between money belonging to the company and money paid for formation work. Investment value and paid-up capital are regulatory and corporate-finance concepts, while notarial work, SABH filing, translations, OSS licensing, tax setup, accounting, and third-party charges form separate commercial cost categories.
Before accepting a proposal, require the provider to state its assumptions, included KBLI activities, corporate deliverables, licensing scope, foreign-document work, address scope, tax and accounting support, post-incorporation services, exclusions, variable charges, and revision rules.
When every provider quotes against the same project assumptions, the comparison becomes far more useful than choosing the lowest unexplained package price.
Request a PT PMA Quote Built Around Your Actual Project
If you are comparing PT PMA setup options in Bali, Bali Legal ID’s PT PMA setup service can assist with a consultation to map the proposed ownership, business activities, KBLI, investment and capital structure, corporate documents, NIB and OSS licensing, tax setup, accounting requirements, and post-incorporation scope before a quotation is finalized.
A useful proposal should make the deliverables, assumptions, exclusions, third-party costs, and recurring compliance work clear before you commit.
For help scoping the documents and next steps for your business or transaction, contact Bali Legal ID about our business setup services in Bali.
Read More: Business Setup Bali for PT PMA, PT PMDN & OSS RBA Registration
FAQ PT PMA setup quote
What should a PT PMA setup quote include?
At minimum, the proposal should define the assumed shareholders and activities, deed and notarial work, SABH establishment, corporate supporting documents, OSS and NIB scope, included licensing work, foreign-document handling, tax setup, post-incorporation support, third-party charges, exclusions, and final deliverables.
Should the IDR 2.5 billion paid-up capital appear as a provider fee?
No. The current regulation sets IDR 2.5 billion as the general minimum placed and paid-up capital per PMA limited liability company unless another rule applies. That is company capital, not the provider’s professional fee.
Does a PT PMA quote that includes SABH also include OSS licensing?
Not automatically. SABH establishment and OSS business licensing are different workstreams. The quotation should state separately whether NIB, each KBLI activity, Standard Certificates, permits, PB UMKU, or other licensing work is included.
Should translation and apostille costs be included?
The quotation should state whether they are included, excluded, or charged when required. Foreign-document requirements vary with the document, shareholder structure, issuing jurisdiction, and intended use, so a provider should not assume one identical document package for every investor.
Does PT PMA setup include tax and accounting services?
Only if the proposal says so. Corporate tax-registration coordination, bookkeeping setup, accounting, tax filings, LKPM support, and financial reporting should be identified as specific deliverables or recurring services rather than assumed from a generic company-formation package.
What is the best way to compare two PT PMA quotations?
Give both providers the same shareholders, ownership, KBLI activities, locations, capital assumptions, address, licensing requirements, tax needs, and post-incorporation scope. Then compare deliverables, exclusions, variable costs, revision rules, handover items, and recurring fees.
References & Sources
- Current Status of Investment and OSS Regulation No. 5 of 2025 — peraturan.bpk.go.id
- Official PT PMA Investment and Capital Provisions in Regulation No. 5 of 2025 — peraturan.bpk.go.id
- Current Status of Ministry of Law Regulation No. 49 of 2025 — peraturan.bpk.go.id
- Official Limited Liability Company Establishment Procedure in Regulation No. 49 of 2025 — peraturan.bpk.go.id
- Current Risk-Based Business Licensing Regulation — peraturan.bpk.go.id
Recommended Next Articles
- PT PMA formation cost and timeline in Bali — balilegalid.com
- legal service quotation checklist for Bali — balilegalid.com
- OSS registration and licensing guide — balilegalid.com