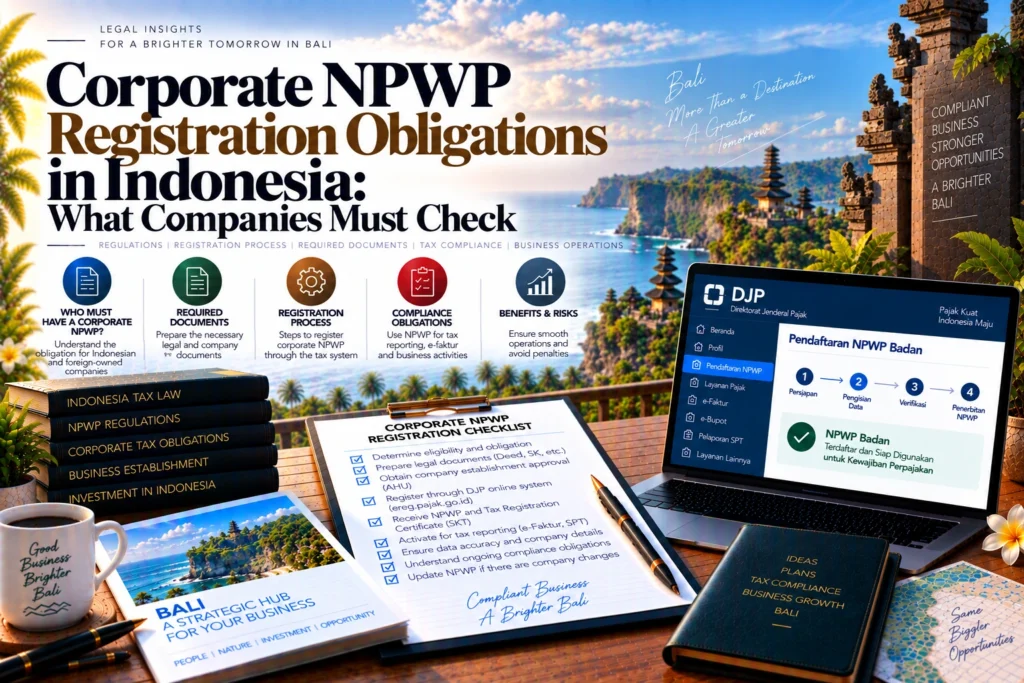
A newly established Indonesian company should treat NPWP registration as a separate tax-administration milestone, not as something automatically replaced by the deed, AHU registration or NIB. The current deadline for a corporate taxpayer is generally no later than one month after the entity is established or becomes domiciled in Indonesia.
Under the current Director General of Taxes Regulation PER-7/PJ/2025, a corporate taxpayer must register no later than one month after being established or becoming domiciled in Indonesia.
The DGT currently marks PER-7/PJ/2025 as active from 21 May 2025, and its closing provisions revoke several older NPWP-administration rules including PER-20/PJ/2018 and PER-04/PJ/2020.
Corporate NPWP Registration Obligations: When Must a Company Register?
For corporate npwp registration obligations, the first control is the company’s legal establishment or Indonesian domicile date.
Do not wait until the company earns its first revenue, hires staff or submits its first annual tax return before checking registration. The corporate registration deadline is tied to the entity’s establishment or Indonesian domicile rather than to the date of its first commercial sale.
A setup timeline should therefore record at least four separate milestones: company establishment, corporate NPWP registration, OSS/NIB licensing and any later PKP registration where the VAT rules require or permit it.
For foreign investors who are still structuring the company itself, Bali Legal ID’s verified PT PMA setup guide provides adjacent incorporation and OSS context; the corporate NPWP remains a separate tax-administration obligation.
NPWP Registration Is Separate From Company Incorporation
An incorporation document creates or records the legal entity. The NPWP identifies that entity within the tax administration so it can carry out its tax rights and obligations.
Treating the two processes as interchangeable can create gaps in the setup file. A company can have its deed and corporate approval while still needing to verify that its taxpayer registration has been properly completed and that its current data is accessible through the tax-administration system.
The wider Coretax administrative framework remains based on PMK 81/2024, and the Ministry of Finance records PMK 1/2026 as its latest, fourth amendment, effective from 22 January 2026.
For investors, the useful question is therefore not simply whether the company exists, but whether its company, tax and licensing records describe the same entity and business position.
Where Is a Corporate Taxpayer Registered?
PER-7/PJ/2025 also provides that a corporate taxpayer registers with the tax office whose jurisdiction covers the actual domicile of the entity.
The same regulation states that the corporate domicile is determined according to the actual circumstances and can be identified from incorporation documents, foreign-head-office appointment documents, business permits or evidence of the business location.
This makes address consistency important. The deed, tax record, OSS profile and real administrative location should be compared rather than maintained as unrelated datasets.
For a Bali business using a registered office, operational premises or several project locations, separate the legal-entity domicile from the question of where each business activity is physically performed. The NPWP domicile analysis should follow the current DGT rules rather than being inferred only from a commercial lease or OSS activity location.
What Documents Are Required for Corporate NPWP Registration?
The document set depends on the kind of entity being registered.
Domestic Corporate Taxpayers
For an Indonesian PT or another domestic corporate taxpayer, prepare the establishment document and any relevant amendments before starting the registration workflow.
The registration data should correspond to the current legal entity. If the company name, legal form, address or other corporate information has changed since incorporation, compare the newest documents with the information being submitted to DGT.
Do not upload an old deed merely because it was the original incorporation document if later amendments materially changed the company’s current information.
Permanent Establishments and Foreign Representative Offices
For a permanent establishment or foreign representative office, the same DGT guidance instead identifies an appointment letter from the foreign head office as the relevant establishment evidence.
This is a different documentary basis from an Indonesian incorporated company. Investors should therefore identify the legal form first and then follow the registration evidence required for that form rather than reusing a PT checklist for every foreign-business presence.
How Corporate NPWP Registration Is Submitted
The current system is designed around electronic tax administration.
PER-7/PJ/2025 provides for electronic taxpayer registration through the Taxpayer Portal, integrated applications or the Contact Center, with non-electronic channels available where electronic registration cannot be completed.
For a corporate taxpayer, the practical preparation work should happen before the online form is submitted. Verify the legal name, establishment documents, domicile, representative information, email address and other data that will be used to create and administer the taxpayer profile.
The registration process should also be treated as the start of tax-account administration. Keep access credentials, authorized representatives and company contact information controlled by the business rather than leaving the tax account dependent on an outdated employee or external party.
NPWP Is Not the Same as PKP
One of the most important distinctions is that corporate NPWP registration does not automatically mean the company is registered as a Pengusaha Kena Pajak.
The DGT registration portal lists Taxpayer Registration and PKP Registration as separate registration-service categories.
NPWP establishes the company’s taxpayer identity and tax-administration position. PKP is a separate VAT status with its own eligibility, mandatory-registration and compliance consequences.
A company can therefore need an NPWP well before it becomes required to register as PKP. Conversely, when the business later meets the relevant PKP conditions or chooses voluntary PKP registration where permitted, that additional status should be handled as its own tax-compliance project rather than assumed from the existence of the NPWP.
For accounting planning, keep these milestones separately documented: NPWP registration date, PKP status if applicable, first tax periods, withholding obligations and annual corporate-income-tax reporting.
What Should Be Updated After Registration?
Obtaining the NPWP is not the final administrative task. The taxpayer record should continue to reflect the real company.
PER-7/PJ/2025 expressly recognizes changes to a corporate taxpayer’s domicile, business activities, capital structure or ownership as taxpayer-data changes that can require the tax record to be updated.
This matters during investment, restructuring and expansion. A new office, change of business activity, shareholder restructuring or capital change can affect several corporate systems at the same time.
Do not update only one database. Compare the deed and AHU records, tax profile, OSS data, accounting master data and operating information after a material corporate change.
A mismatch may not immediately stop daily operations, but it can make later tax filings, licensing amendments, due diligence or business closure more difficult to reconcile.
Corporate NPWP Readiness Checklist for Bali Businesses
First, record the company’s establishment date and calculate the one-month registration window under the current rule.
Second, identify the correct entity type. A domestic PT, permanent establishment and foreign representative office do not necessarily use the same establishment evidence.
Third, confirm the company’s actual domicile. Compare the deed, administrative office and business documentation used to support the tax-registration jurisdiction.
Fourth, prepare the latest establishment documents and amendments. The registration file should represent the company as it exists now, not only as it existed on incorporation day.
Fifth, control the electronic registration account and contact details. Use an email address and company-access process that can remain available when employees, directors or advisers change.
Sixth, distinguish NPWP from PKP. Do not treat the corporate taxpayer number as proof that the company has entered the VAT regime.
Seventh, connect registration to the accounting setup. Taxpayer identity, chart of accounts, withholding processes, tax-payment administration and annual reporting should use consistent corporate information.
Eighth, review the tax record after material company changes. Address, activity, capital and ownership changes should trigger a data-consistency check across the company’s corporate, tax and OSS systems.
Finally, retain the registration and amendment evidence as part of the permanent corporate compliance file. Investors conducting due diligence should be able to reconcile the taxpayer identity with the current legal entity without reconstructing the history from incomplete records.
Conclusion
Corporate NPWP registration is an early company-compliance obligation, not a substitute for incorporation, OSS licensing or PKP registration. Under current PER-7/PJ/2025, a corporate taxpayer generally must register no later than one month after establishment or becoming domiciled in Indonesia.
The practical compliance task continues after the number is issued. Keep the corporate domicile, establishment records, business activities, capital and ownership information aligned with the DGT record, and treat later PKP registration as a separate VAT-status decision.
Once the taxpayer registration file is organised, connect it with the company tax compliance review and the accounting and tax recordkeeping workflow so registration details and ongoing records remain consistent.
Align Company, Tax and Licensing Records From the Start
If you are establishing or restructuring a company in Bali, Bali Legal ID can be consulted to coordinate the company setup, tax-registration and wider compliance review.
Tax consulting, accounting services and company setup support can help keep the corporate documents, NPWP data, accounting records and licensing information aligned; no separate verified service URL was supplied for this package.
For help scoping the documents and next steps for your business or transaction, contact Bali Legal ID about our financial consultant services in Bali.
Read More: Financial Consultant in Bali for Tax, Accounting & Financial Reporting Services
FAQ corporate npwp registration obligations
When must an Indonesian company register for an NPWP?
Under current PER-7/PJ/2025, a corporate taxpayer generally must register no later than one month after being established or becoming domiciled in Indonesia.
Does a company automatically receive PKP status when it obtains an NPWP?
No. DGT treats taxpayer registration and PKP registration as separate administrative processes.
What document does a domestic company need for corporate NPWP registration?
Current DGT guidance identifies the deed of establishment or other establishment document and its amendments as the core evidence for a domestic corporate taxpayer.
Where is a company registered for tax purposes?
PER-7/PJ/2025 provides that a corporate taxpayer registers with the tax office whose jurisdiction covers the entity’s actual domicile.
Can corporate NPWP registration be completed electronically?
Yes. The current rule provides electronic channels through the Taxpayer Portal, integrated applications and the Contact Center, with non-electronic channels available where electronic registration cannot be completed.
Should NPWP data be updated when company information changes?
Yes. Current DGT rules recognize changes such as corporate domicile, business activities, capital structure and ownership as taxpayer-data changes that can require the tax record to be updated.
References & Sources
- Director General of Taxes Regulation PER-7/PJ/2025 — NPWP and PKP Administration — stats.pajak.go.id
- Directorate General of Taxes — Corporate Taxpayer Registration — pajak.go.id
- Directorate General of Taxes — Registration Services — pajak.go.id
- Minister of Finance Regulation No. 81 of 2024 — Coretax Administration Framework — jdih.kemenkeu.go.id
- Minister of Finance Regulation No. 1 of 2026 — Fourth Amendment to the Coretax Administration Framework — jdih.kemenkeu.go.id
Recommended Next Articles
- PT PMA company setup and OSS planning in Bali — balilegalid.com